Budget vs Actual Analysis: How to Run a Monthly Variance Review
It’s the first Tuesday of the month. You open your bank app, see a lower balance than you expected, and feel that familiar knot: where did it go? You made a budget in January. You just never looked at it again.
A budget vs actual analysis fixes that. Once a month, you put what you planned next to what really happened, find the gaps that matter, and decide what to do about them. It takes about 30 minutes, and it’s built for solo owners, freelancers, Etsy sellers and makers who don’t have a finance team but still want to stop guessing.
This isn’t paperwork. It’s the moment your budget stops being a wish list and starts steering your business.

What is a budget vs actual analysis?
It’s a side-by-side comparison of your planned numbers and your real numbers for the same period, usually a month. For each line (sales, materials, fees, marketing, software) you record three things:
- Budget: what you expected to earn or spend.
- Actual: what your books say happened.
- Variance: the difference, in dollars and as a percentage.
A variance isn’t good or bad on its own. Spending $150 more on ads is great if it brought in $900 of extra sales, and a warning sign if it brought in nothing. The review is where you find out which one it was.
If you don’t have a budget yet, start with our guide to building a simple small business budget. You need one plan to compare against, even a rough one.
Key idea: A budget you never compare to reality is just a guess with nicer formatting.
How to run a monthly variance review step by step
Block 30 minutes in the first week of each month. Bring your bank and card statements, your sales platform payout report and last month’s budget.
- Close the month first. Make sure every sale, fee and expense from last month is recorded and your bank balance matches your books. If you reconcile monthly, this step is already done.
- Pull actuals by category. Use the same categories as your budget. If your budget says “Marketing” but your books split it into “Pinterest” and “Etsy Ads,” add them up so you compare like with like.
- Calculate the variance. Variance $ = Actual − Budget. Variance % = Variance $ ÷ Budget × 100. A spreadsheet does this in one formula per row.
- Flag only what matters. Set a simple rule, for example: investigate any line that is off by more than 10% and more than $100. Small lines with big percentages ($12 over on a $20 budget) can wait.
- Ask “why” for each flagged line. Write one sentence: timing (a bill landed early), volume (more orders, more materials), price (supplier raised costs) or a one-off (a new tool).
- Check ratios, not just dollars. Compare each cost to revenue. Materials at 25% of sales in your plan but 30% in reality is a margin problem, even if the dollar gap looks small.
- Decide one action per flag. Adjust next month’s budget, change a habit, or accept the variance and note why.
- Update your forecast. Carry what you learned into next month’s numbers so the plan gets more accurate every cycle.

Example: a candle maker’s October review
Picture a candle maker in Ohio, a typical example, reviewing October. She planned $6,000 in sales. Here’s what her sheet shows:
| Line | Budget | Actual | Variance $ | Variance % |
|---|---|---|---|---|
| Revenue | $6,000 | $5,400 | −$600 | −10.0% |
| Materials | $1,500 | $1,620 | +$120 | +8.0% |
| Shipping supplies | $300 | $345 | +$45 | +15.0% |
| Etsy and payment fees | $650 | $590 | −$60 | −9.2% |
| Marketing | $250 | $400 | +$150 | +60.0% |
| Software | $120 | $120 | $0 | 0.0% |
| Total expenses | $2,820 | $3,075 | +$255 | +9.0% |
| Net profit | $3,180 | $2,325 | −$855 | −26.9% |
Using her “more than 10% and more than $100” rule, two lines get flagged:
- Revenue (−$600, −10%). Why? A scent she expected to sell well launched two weeks late. Action: move it into November’s plan instead of writing it off.
- Marketing (+$150, +60%). Why? She tested a second ad channel. Action: check whether those sales covered the cost before repeating it.
Then she checks ratios. Materials were planned at 25% of revenue ($1,500 ÷ $6,000) but came in at 30% ($1,620 ÷ $5,400). A supplier price increase hid inside a line that only looked 8% over. That’s the most important finding of the month, and it points straight at a pricing review. Our guide to margin vs markup helps here.
Notice what happened: a $855 profit gap became three specific decisions. That’s the whole point.
Common mistakes to avoid
- Reviewing before the month is closed. Missing fees or late receipts create fake variances and real stress.
- Using different categories in the budget and the books. Pick one list and stick to it. Our expense categories guide is a good starting set.
- Chasing every small difference. A threshold rule keeps the review to 30 minutes instead of three hours.
- Treating the budget as fixed forever. If you learn something real, update the plan. A budget is a tool, not a contract.
- Looking only at profit, not cash. A month can be profitable and still leave your bank account thin. Read cash flow vs profit to see why.
- Skipping the “why.” Numbers without a reason don’t change behavior. One sentence per flag is enough.
Key idea: The goal isn’t to hit your budget perfectly. It’s to be surprised a little less each month.
Your 15-minute action plan
You don’t need to wait for month-end to start. Do this today:
- [ ] Put your current budget categories in column A of a spreadsheet.
- [ ] Add columns for Budget, Actual, Variance $ and Variance %.
- [ ] Enter last month’s actual numbers from your bank and sales reports.
- [ ] Write your threshold rule at the top (for example, 10% and $100).
- [ ] Highlight every line that crosses it and write one “why” sentence next to it.
- [ ] Put a recurring 30-minute “variance review” on your calendar for the first week of each month.
FAQ
What is a good variance percentage in a budget?
There’s no universal number, but many small businesses investigate anything over 5–10% on important lines. Pair the percentage with a dollar minimum so you don’t waste time on tiny categories.
How often should a small business compare budget to actual?
Monthly works best for most solo owners. It’s frequent enough to catch problems early and long enough for the numbers to mean something. In a busy season you may want a quick weekly check on sales and ad spend.
Is a favorable variance always good?
No. Spending less than planned on marketing looks favorable but may explain why sales dipped. Always ask what caused the variance before celebrating it.
What’s the difference between a budget vs actual report and a P&L?
A profit and loss statement shows what happened. A budget vs actual report shows what happened compared with what you planned. If you’re new to the P&L itself, start with how to read a profit and loss statement.
The bottom line
A monthly variance review is one of the simplest habits that separates businesses that drift from businesses that steer. Thirty minutes, one table, a few honest “whys,” and you walk away knowing exactly what to change next month.
Start with last month’s numbers today, even if your budget was rough. The second review is always easier than the first. The U.S. Small Business Administration’s guide to managing your business finances is a helpful companion as you build the habit.
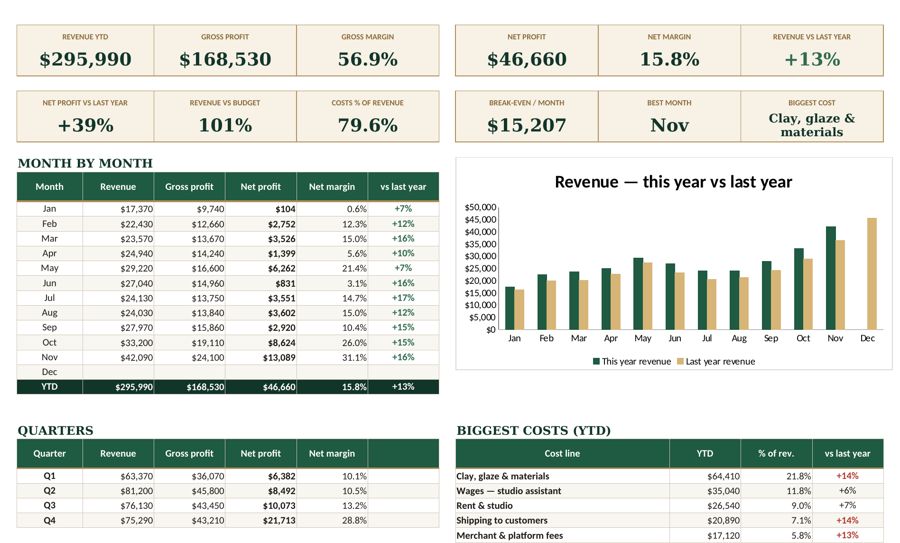
If you’d rather not build the sheet from scratch, the Fyscale Profit & Loss Analyzer already has a budget vs actual view set up, so you can drop in your numbers and get straight to the decisions.
Tools mentioned in this article
Keep reading
This article is general information for US small businesses, not tax, legal or accounting advice. Check current IRS guidance or ask a qualified professional about your situation.