How to Build a 13-Week Cash Flow Forecast
A profit and loss statement tells you how the business did last month. It does not tell you whether you can make payroll, pay a supplier or cover a tax payment three weeks from now. That is the job of a 13 week cash flow forecast: a week-by-week view of the cash you expect to come in and go out over the next quarter. It is simple enough to build in a spreadsheet in an hour, and it is one of the best early-warning tools a small business can have. Here is how to build one, with a worked example you can copy.
Why 13 weeks?
Thirteen weeks is one quarter. It is short enough that your estimates stay fairly accurate, and long enough to see trouble coming while you can still do something about it, like delaying a purchase, chasing an invoice or arranging credit before you need it.
Weekly buckets matter, too. A monthly forecast can show a healthy month-end balance while hiding the Tuesday when your account dips below zero because rent and an inventory bill landed before customer payments did. If that sounds familiar, our guide to cash flow vs profit explains why profitable businesses still run short.
What you need before you start
- Your current bank balance in all business accounts (not including money already set aside for taxes, unless you plan to spend it)
- Open invoices and when you realistically expect each to be paid
- Recent sales history by week, especially for the same season last year if you have it
- Recurring bills: rent, software, insurance, loan payments, contractors
- Planned one-time costs: inventory orders, equipment, annual renewals, estimated tax payments
- Your minimum cash buffer: the lowest balance you are comfortable holding
How to build a 13 week cash flow forecast, step by step
Step 1: Set up the columns
Create one column per week, labeled with the Monday start date. Use rows for opening cash, each type of cash in, each type of cash out, net cash flow and closing cash.
Step 2: Enter the opening balance
Week 1’s opening cash is today’s bank balance. Every later week’s opening cash equals the previous week’s closing cash. In a spreadsheet, that is one formula copied across.
Step 3: Forecast cash in, by week
Be realistic about timing. List cash on the date it actually arrives in your bank, not the date you make the sale or send the invoice. Marketplace payouts often arrive on a schedule, and clients on net 30 terms frequently pay late. If a client usually pays 10 days late, forecast it 10 days late.
Step 4: Forecast cash out, by week
Put each bill in the week you will pay it. Include owner’s draws, because that cash leaves the business too. Do not forget the big, infrequent items: the fourth quarterly estimated tax payment for tax year 2026 is due January 15, 2027, which falls inside a forecast that starts in late October. Our guide to quarterly estimated taxes lists all the dates, and the IRS page on estimated taxes explains who needs to pay.
Step 5: Calculate net flow and closing cash
Net cash flow = total cash in − total cash out
Closing cash = opening cash + net cash flow
Step 6: Flag any week below your buffer
Use conditional formatting to turn a cell red when closing cash falls below your minimum. Those red weeks are your action list.
Worked example: an Etsy shop heading into the holidays
Lena sells handmade goods on Etsy. She starts with $6,000 in business checking and wants to keep at least $2,000 at all times. Her regular weekly outflows (materials, shipping supplies, ads, software and her owner’s draw) are about $2,600, dropping to $2,400 after the holidays. On top of that:
- Week 1: holiday inventory order, first payment of $3,900
- Week 2: second inventory payment of $2,600
- Weeks 4, 7 and 11: $800 to a part-time contractor
- Week 12: $3,000 fourth-quarter estimated tax payment (due Jan 15, 2027)
| Week | Starts | Opening | Cash in | Cash out | Closing |
|---|---|---|---|---|---|
| 1 | Oct 26 | $6,000 | $2,500 | $6,500 | $2,000 |
| 2 | Nov 2 | $2,000 | $2,800 | $5,200 | −$400 |
| 3 | Nov 9 | −$400 | $3,200 | $2,600 | $200 |
| 4 | Nov 16 | $200 | $3,600 | $3,400 | $400 |
| 5 | Nov 23 | $400 | $5,800 | $2,600 | $3,600 |
| 6 | Nov 30 | $3,600 | $6,400 | $2,600 | $7,400 |
| 7 | Dec 7 | $7,400 | $6,900 | $3,400 | $10,900 |
| 8 | Dec 14 | $10,900 | $6,200 | $2,600 | $14,500 |
| 9 | Dec 21 | $14,500 | $4,100 | $2,600 | $16,000 |
| 10 | Dec 28 | $16,000 | $1,800 | $2,400 | $15,400 |
| 11 | Jan 4 | $15,400 | $1,500 | $3,200 | $13,700 |
| 12 | Jan 11 | $13,700 | $1,600 | $5,400 | $9,900 |
| 13 | Jan 18 | $9,900 | $1,700 | $2,400 | $9,200 |
Over 13 weeks, Lena brings in $48,100 and spends $44,900, so she ends the quarter $3,200 ahead at $9,200. On a monthly or quarterly view, she looks fine. The weekly view shows the real problem: her account goes negative in week 2 and stays below her $2,000 buffer through week 4, because she pays for holiday inventory before holiday sales arrive.
The fix
Lena asks her supplier to split the second $2,600 payment into two payments of $1,300 in weeks 5 and 6, once sales pick up. Here is the revised early stretch:
| Week | Opening | Cash in | Cash out | Closing |
|---|---|---|---|---|
| 2 | $2,000 | $2,800 | $2,600 | $2,200 |
| 3 | $2,200 | $3,200 | $2,600 | $2,800 |
| 4 | $2,800 | $3,600 | $3,400 | $3,000 |
| 5 | $3,000 | $5,800 | $3,900 | $4,900 |
| 6 | $4,900 | $6,400 | $3,900 | $7,400 |
From week 6 on, nothing changes: she is back at $7,400, because the same money still leaves the business, just later. No week falls below her buffer. Other options she could have used: ordering in two smaller batches, running an early-bird promotion to pull sales forward, or trimming ad spend for two weeks.
Keep it rolling every week
A 13 week forecast is a living tool. Once a week:
- Replace last week’s forecast with actual numbers.
- Note big differences and why they happened.
- Drop the finished week and add a new week 13 at the end.
- Update open invoices and upcoming bills.
Comparing forecast to actual each week is how your forecast gets more accurate over time. If late-paying clients are the main source of misses, a polite unpaid invoice follow-up email is often the quickest way to pull cash back into the right week.
Common mistakes to avoid
- Forecasting sales instead of cash. Use the date money hits your bank.
- Forgetting irregular costs such as annual renewals, insurance and estimated taxes.
- Being too optimistic. When in doubt, assume income arrives later and bills arrive sooner.
- Building it once and abandoning it. The value comes from the weekly update.
Bottom line
- [ ] Start with today’s real bank balance
- [ ] One column per week for 13 weeks
- [ ] Cash in on the day it arrives; cash out on the day you pay
- [ ] Include owner’s draws and estimated tax payments
- [ ] Set a minimum buffer and flag weeks below it
- [ ] Update every week and roll forward
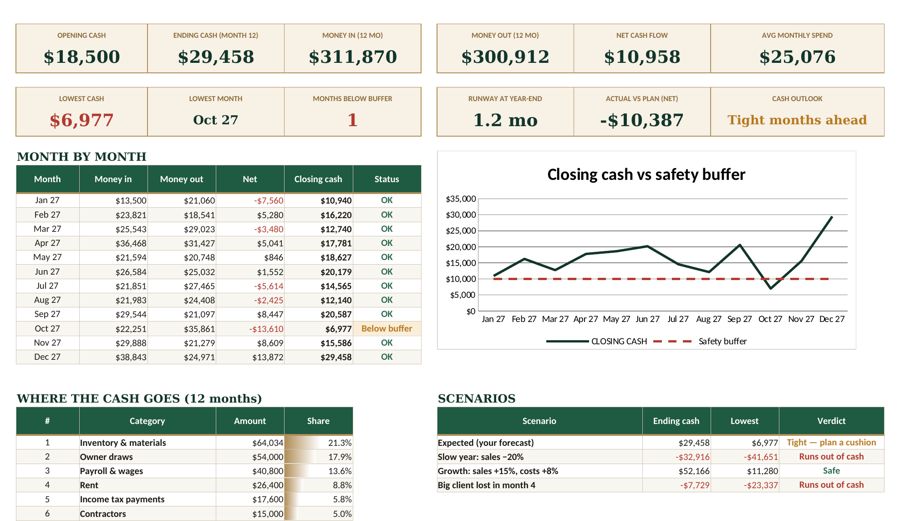
If you would rather not build the formulas yourself, the Fyscale cash flow forecast spreadsheet has the weekly layout, running balance and buffer warnings set up already. Either way, 20 minutes a week with a forecast like this can save you from a cash crunch you never saw coming.
Tools mentioned in this article
Keep reading
This article is general information for US small businesses, not tax, legal or accounting advice. Check current IRS guidance or ask a qualified professional about your situation.