IRS Expands Retirement Plan Self-Correction Rules and Creates New IRA Fix Program
The Treasury Department and the IRS on October 22 released an overhaul of the program employers use to fix mistakes in workplace retirement plans, along with a brand-new correction program for individual retirement accounts. Revenue Procedure 2026-34 updates the Employee Plans Compliance Resolution System (EPCRS) and takes effect immediately, while Revenue Procedure 2026-33 creates an IRA Compliance Resolution System (ICRS) that starts May 1, 2027.
For small businesses that sponsor a 401(k), SEP or SIMPLE IRA plan, the headline change is that more common errors can now be fixed in-house, without filing with the IRS or paying a user fee, as long as the business acts within set time limits.
What happened
- EPCRS gets a rewrite. According to the IRS news release (IR-2026-126), Rev. Proc. 2026-34 replaces Rev. Proc. 2021-30, the rulebook plan sponsors have relied on since 2021. EPCRS includes the Self-Correction Program (SCP), the Voluntary Correction Program (VCP) and the Audit Closing Agreement Program.
- Self-correction is broader. The revenue procedure lets sponsors self-correct “Eligible Inadvertent Failures” without needing a favorable IRS determination letter for qualified and 403(b) plans. It also opens SCP to certain plan document, demographic and employer eligibility failures and to plan loan failures.
- A clearer deadline. A self-correction is treated as made within a reasonable period if it is finished by the later of the last day of the third plan year after the year the failure occurred, or 18 months after the problem was identified.
- Missed deferrals in auto-enrollment plans. Implementing the SECURE 2.0 Act, the guidance makes permanent a safe harbor for fixing missed employee deferrals in plans with automatic enrollment or escalation, without a required employer “make-up” contribution (QNEC), and extends it to SEP and SIMPLE IRA plans and to employees who have left.
- Overpayments. Sponsors generally do not have to claw back inadvertent benefit overpayments or make a corrective contribution, with exceptions for certain limit-related failures; overpayments of $250 or less are excepted.
- New IRA program. ICRS, created under SECURE 2.0, will let IRA custodians and owners request correction of certain inadvertent failures caused by service-provider errors. Requests to waive the 60-day rollover deadline, now handled through private letter rulings, will move to ICRS during 2027 and 2028.
IRS CEO Frank J. Bisignano said the changes “simplify and speed up” how these errors get corrected. Treasury and the IRS are inviting public comments on both programs; deadlines are listed in each revenue procedure.
Why it matters for small businesses
- Lower cost of mistakes. Late deposits of deferrals, missed eligible employees or loan errors are common in small plans. Fixing more of them through self-correction can avoid VCP user fees and professional filing costs.
- Time limits now matter more. The benefit depends on catching and fixing errors promptly, so sloppy payroll records can turn a free fix into a paid one.
- SEP and SIMPLE IRA owners are covered. Many solo owners and very small employers use these simpler plans, and the expanded safe harbor applies to them too.
What you can do now
- Review this year’s payroll deferrals against what employees elected and confirm deposits reached the plan on time.
- Check eligibility. Make sure every employee who met your plan’s age and service rules was offered the plan.
- Keep written records of any error you find, the date you found it and how you fixed it; documentation is central to self-correction.
- Ask your plan provider or CPA whether any past issue now qualifies for self-correction under the new rules.
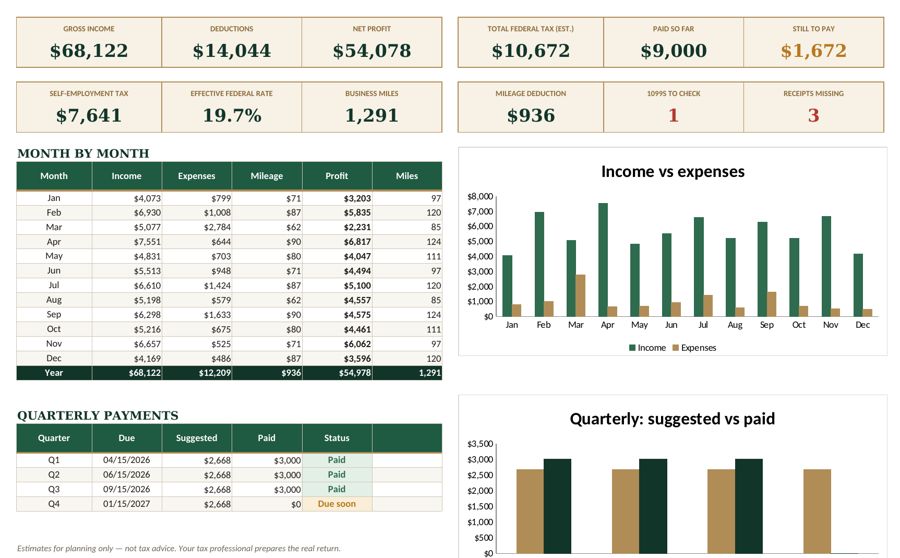
- Tighten your books. Clean records make errors easier to spot. Our guide to small business bookkeeping walks through a simple monthly routine.
This brief is for general information only and is not tax or legal advice. Confirm details against the full revenue procedures or with a qualified professional.
Sources
- IRS — Treasury, IRS update retirement plan correction program and establish correction program for individual retirement accounts (IR-2026-126)
- IRS — Revenue Procedure 2026-34 (EPCRS)
- Current Federal Tax Developments — Employee Plans Compliance Resolution System Overhaul: An Analysis of Revenue Procedure 2026-34
Tools mentioned in this article
More news
Fyscale news briefs summarize public information from the sources listed above; read our editorial policy. This article is general information for US small businesses, not tax, legal or accounting advice. Check current IRS guidance or ask a qualified professional about your situation.